Offset mortgage or revolving credit: where should your savings sit?
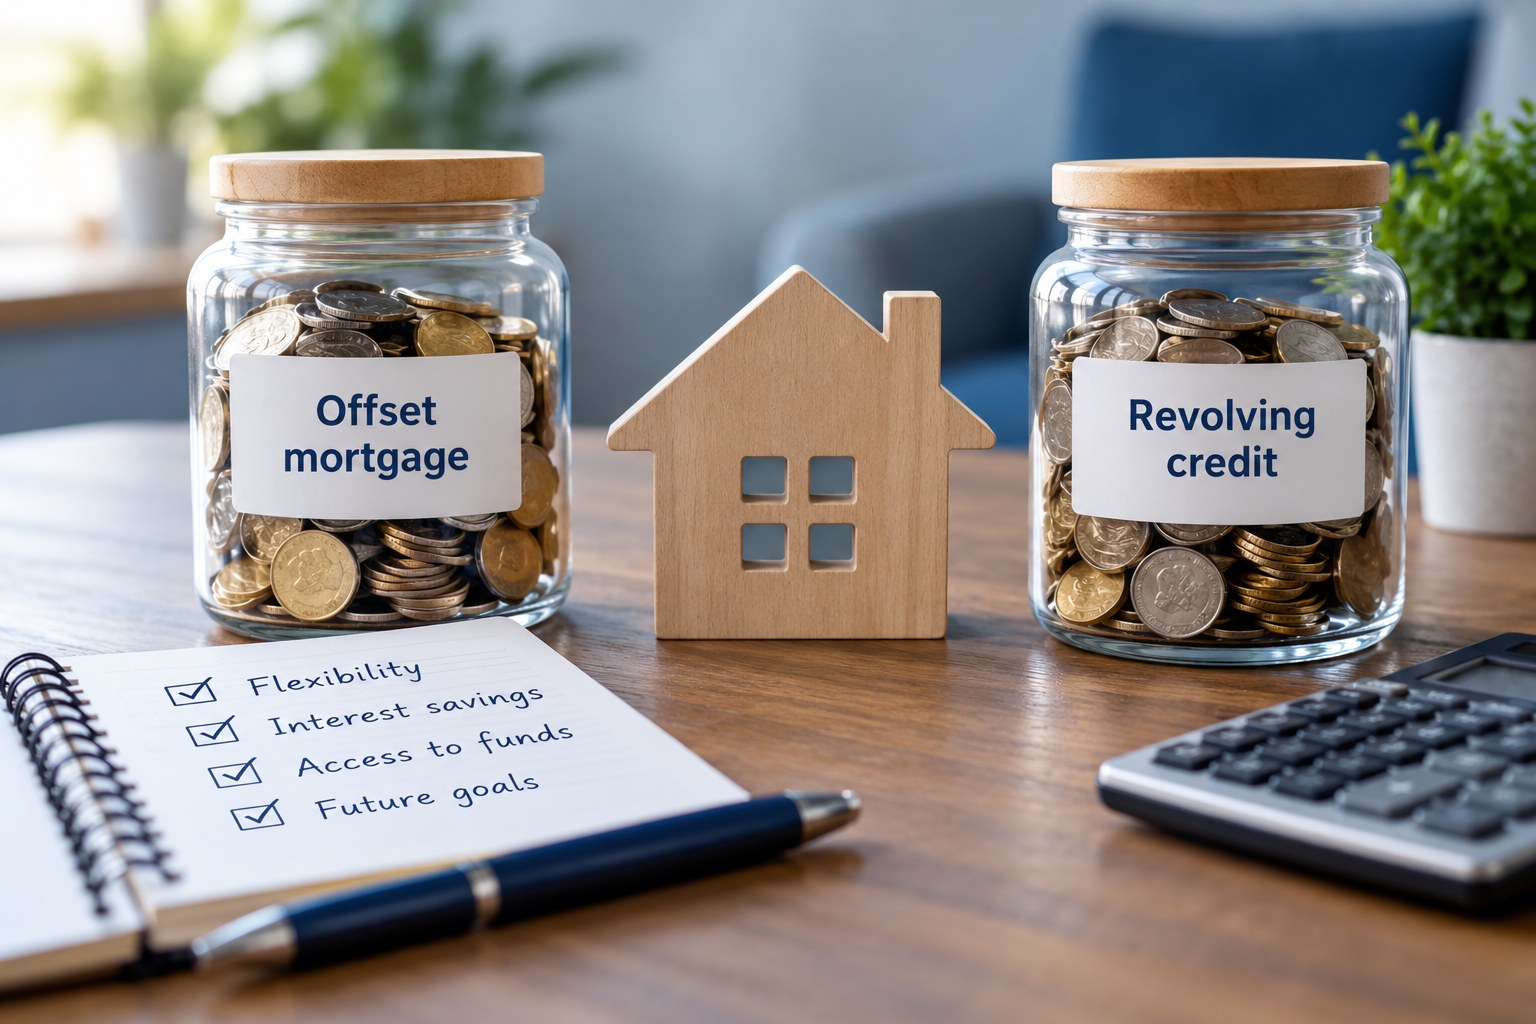
Money in your everyday and savings accounts could be doing more than waiting for the next bill. With the right home-loan structure, those balances may help reduce the mortgage interest you pay.
Two options that New Zealand homeowners often hear about are offset mortgages and revolving credit. Both can reduce interest, but they work differently. The better fit depends on your income, spending habits, savings and how much flexibility you actually need.
What is an offset mortgage?
An offset mortgage connects eligible everyday or savings accounts to a portion of your home loan. The bank uses the combined balances in those linked accounts to reduce the loan balance on which it calculates interest.
For example, imagine you have a $70,000 offset home-loan portion and $20,000 across eligible linked accounts. While those balances remain the same, you would generally pay interest on $50,000 rather than $70,000.
The savings have not actually been paid into the loan. They remain accessible in the linked accounts. Under many offset products, your required mortgage repayments stay the same, allowing more of each payment to go towards the principal when interest costs are lower.
The interest calculation and which accounts qualify depend on your bank’s product terms.
What is revolving credit?
Revolving credit works more like a large overdraft secured against your home. Income goes into the account and reduces the amount you owe. Expenses and withdrawals increase it again. Interest is generally calculated on the outstanding daily balance.
This can suit people who actively manage their cash flow and regularly hold surplus funds. It also requires discipline. If you repeatedly redraw everything you pay in, the balance may not fall as planned.
Some revolving-credit products have no scheduled principal repayments, and their fees, limits and interest rates differ by lender.
The important difference is how you manage money
With an offset loan, your savings and spending accounts remain separate from the mortgage. You can see the money allocated to bills, emergencies and future expenses while still reducing the interest charged on the linked mortgage portion.
With revolving credit, everyday money moves in and out of the loan account itself. This may be convenient if your income and expenses fluctuate, but the available credit can make it tempting to spend money you intended to keep.
Neither option is automatically better. A structure that saves interest on paper will only help in practice if it suits the way you handle money.
Could you combine flexibility with fixed-rate certainty?
You do not necessarily need to put your whole mortgage on a flexible loan. One approach may be to keep a smaller portion on offset or revolving credit, with the remainder fixed for an agreed term.
The appropriate split depends on the amount of cash you typically retain, your budget, the interest rates and fees available, and whether you expect to use those funds.
A flexible portion that is much larger than your usual savings may leave too much debt exposed to a floating interest rate. On the other hand, fixing everything can limit the ways you use spare cash to reduce interest.
Five questions to ask before changing your structure
1. How much money genuinely stays in our accounts from month to month?
2. Do we want our savings kept separate from our home-loan balance?
3. How disciplined are we about not redrawing available credit?
4. What are the floating rates, account fees and eligibility requirements?
5. Would a smaller flexible portion alongside fixed lending suit our goals better?
Remember to consider the interest your savings may otherwise earn, whether any fixed-rate break costs would arise, and how the structure fits your emergency buffer.
Build a mortgage plan around your real life
Your mortgage should work with your household accounts, not against them. The right combination of fixed lending, accessible savings and flexible repayments may help you reduce interest while keeping money available for the things that matter.
At Bricks & Mortgages, we help clients review their full mortgage structure and create a personalised roadmap towards becoming mortgage-free sooner.
If you have savings sitting alongside a home loan, contact us for a mortgage structure review before making changes.